
Wondering how you can improve your chances of getting a competitive mortgage rate in Ottawa? Your rate depends on several factors, including your credit history, down payment, and financial situation. Some of these factors are within your control, and making a few adjustments before applying could help you access better mortgage options. Whether you’re buying your first home or preparing for your next move, here are seven practical tips to help you secure a competitive mortgage rate in Ottawa.
1. Improve Your Credit Score
Your credit score helps lenders assess how you’ve managed borrowed money in the past, and a strong credit history can improve your eligibility for competitive mortgage rates. Before applying, review your credit report and check for any errors. Paying bills on time, reducing credit card balances, and avoiding unnecessary new debt can help strengthen your financial profile. Remember, you don’t need perfect credit to qualify for a mortgage. However, understanding your credit history can help you choose the right options when approaching lenders.
2. Manage Your Existing Debt
Lenders consider more than just your credit score when reviewing a mortgage application. They also assess your existing financial commitments, including car loans, credit cards, and lines of credit. In Canada, lenders use debt-service ratios to determine how much of your income would go toward housing expenses and other debt payments. Reducing outstanding debt may improve your mortgage eligibility and increase your options.
3. Consider Your Down Payment and Mortgage Insurance
Your down payment affects how much you can borrow and which mortgage products are available. In Canada, buyers with less than a 20% down payment generally need mortgage default insurance. Although this insurance adds to your borrowing costs, insured mortgages sometimes qualify for lower interest rates because they present less risk to lenders.
Putting down 20% or more usually avoids the insurance premium, but doesn’t automatically guarantee a better mortgage rate. Also budget for Ontario land transfer tax, legal fees, inspections, and other closing costs. The right down payment should leave you financially comfortable after purchasing your home.
4. Get Pre-Approved Before Comparing Mortgage Offers
Mortgage pre-approval is an important step when preparing to buy a home. It estimates how much you may qualify to borrow based on your income, credit history, debts, and down payment. Some lenders also offer rate holds that can protect you against potential rate increases for a set period. However, pre-approval isn’t a guarantee of final financing. Your lender must still review the property and confirm your financial information.
5. Compare Mortgage Rates From Multiple Canadian Lenders
Different mortgage lenders offer different rates, qualification requirements, and mortgage features. Your bank may offer a competitive rate, but it’s worth comparing other options before you decide. Remember that advertised rates don’t always apply to every borrower. Some offers apply only to specific mortgage types, down payments, or qualification criteria.
As a mortgage broker, I work with multiple Canadian lenders, including banks, credit unions and other mortgage providers. This allows me to compare available mortgage products based on your unique financial circumstances. Contact me, and I’ll help you compare options from multiple lenders so you can choose a mortgage that fits your needs.
6. Explore Mortgage Types, Terms, and Features
The lowest advertised rate isn’t necessarily the best mortgage for your lifestyle. When comparing mortgage deals, consider the full mortgage agreement. A fixed-rate mortgage offers a consistent interest rate throughout your term, whereas a variable-rate mortgage can change as your lender adjusts its prime rate. The mortgage term is the length of your contract, while amortization is the estimated time needed to repay your mortgage. Consider these factors together when choosing a mortgage.
Other important features include prepayment privileges, portability, and penalties for breaking your mortgage early. These details can make a big difference if you decide to sell your home, refinance, or want to make extra payments.
7. Look at the Total Cost of Your Mortgage
A competitive mortgage rate can reduce interest costs, but it shouldn’t be the only factor you consider. Compare payment amounts, mortgage restrictions, potential penalties, and overall borrowing costs before choosing a lender. For example, a slightly higher rate might offer more flexibility if you plan to move before your term ends. A longer amortization may reduce your regular payments but increase the total interest you pay over time. The goal is to find a mortgage that fits both your current budget and future plans.
Let’s Find a Mortgage That Works for You
Getting a competitive mortgage rate starts with preparation, careful comparisons, and the right guidance. Taking time to review your finances and understand the differences between mortgage offers can help you avoid unnecessary costs and choose terms that fit your current and future plans.
With over 20 years of mortgage experience and access to dozens of lenders, I can help you explore mortgage options suited to your financial goals. If you’re planning to buy a home in Ottawa, get in touch and I’ll help you compare your options.
Recent Posts
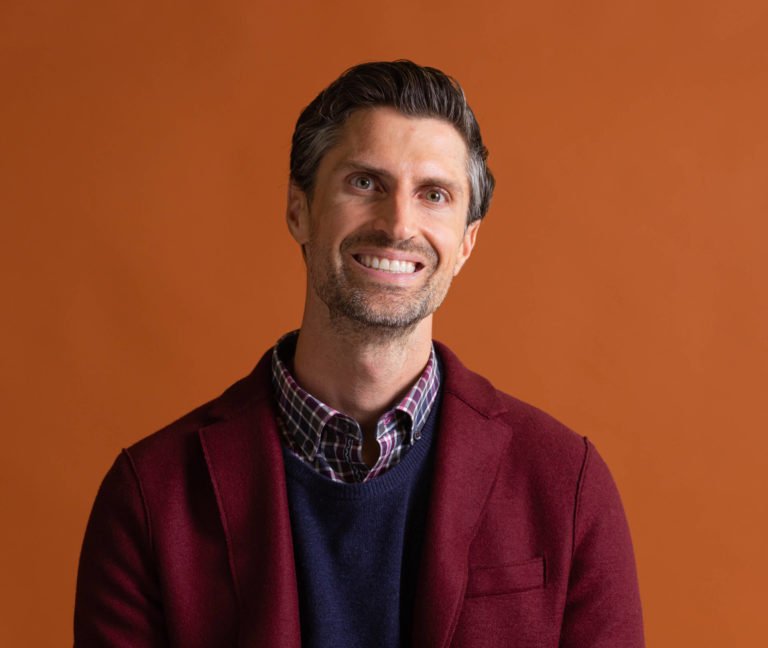
Andrew Thake is a seasoned mortgage broker with over 15 years of industry experience. He’s assisted more than 2,200 clients in finding their ideal mortgage solutions. Recognized for his excellence, Andrew has received high honours and awards, including the National Rookie of the Year from TD Canada Trust and recognition as a Top 10 Ottawa Mortgage Broker in 2023. He has also been inducted into the Hall of Fame at Dominion Lending Centres and has consistently received their Platinum Award during his tenure as a mortgage broker.
Andrew’s dedication lies in serving his clients and prioritizing their needs with an empathetic approach. Throughout the application process, he provides tailored, informed, and efficient services to ensure the best mortgage solutions for his client’s unique circumstances. The best part of Andrew’s job is when he gets to see the joy on his clients’ faces following their mortgage approval.