You may have good credit, stable employment, a high income and a down payment saved, so being declined for a mortgage can come as a surprise.
The reality is that lenders look at much more than your income and credit score. Your debts, employment history, down payment, the property itself and even the lender you apply with can affect the decision.
If you’re buying a home in Ottawa or elsewhere in Ontario, understanding these potential roadblocks before you apply can help you prepare. And if you’ve already been declined for a mortgage, it doesn’t necessarily mean homeownership is out of reach. Sometimes, the issue is simply finding out what caused the decline and determining whether there is another appropriate path forward.
Reasons Why You May Be Declined for a Mortgage
Mortgage approval is based on your overall financial picture as well as the property you want to purchase. Here are some reasons I see that may cause an application to run into difficulties.
1. The Property You Are Buying
It’s easy to assume that mortgage approval is entirely about the borrower, but the lender also needs to be comfortable with the property securing the mortgage.
Certain properties can be more difficult to finance. Depending on the lender, that could include very small condo units, rural properties, mobile or manufactured homes, properties on leased land, unusual construction types or homes that require substantial repairs.
A lender may consider factors such as the property’s condition, location, marketability and whether it meets that lender’s specific guidelines.
This is one reason I recommend discussing an unusual property with a mortgage professional before getting too far into the purchase process. You could be financially qualified for a mortgage but discover that the property itself doesn’t fit a particular lender’s requirements.
2. Your Credit Score or Credit History
Paying your bills on time is important, but it isn’t the only factor that can affect your credit profile.
Your credit report provides lenders with information about how you’ve managed borrowed money over time. High balances relative to your available credit, missed or late payments, accounts sent to collections and other credit issues can potentially make qualification more difficult.
Even if you consider yourself financially responsible, it’s worth reviewing your credit before applying for a mortgage. Errors or issues you weren’t aware of can sometimes appear on a credit report.
Your credit score is also only one part of the picture. Lenders can consider the overall history behind that number when assessing an application.
3. You Don’t Have Enough Established Credit History
Having no major problems on your credit report isn’t necessarily the same as having a well-established credit history.
A lender wants enough information to assess how you’ve handled credit over time. Someone who has only recently started using credit, for example, may have a relatively limited record for the lender to review.
This can affect younger borrowers, newcomers to Canada and people who have traditionally avoided borrowing money. Depending on the mortgage and lender, alternative ways to demonstrate creditworthiness may be available.
The important point is that a thin credit file doesn’t automatically mean you’ve managed your money poorly. It can simply mean the lender has less information available when assessing your application.
4. There Are Questions About Your Down Payment
Having enough money in your account isn’t always enough. Your lender may also need documentation showing the source of your down payment.
For example, funds might come from your savings, investments, proceeds from selling another property or an eligible gift. The documentation required will depend on the source of those funds and the lender’s requirements.
Moving large sums between accounts shortly before applying can complicate the paper trail. Undocumented cash deposits can create similar questions because a lender may need to establish the origin of the funds.
Rather than assuming a particular source will or won’t be accepted, I recommend talking to me before moving or borrowing money for your down payment. There are mortgage products in which certain non-traditional down payment sources may be considered, but eligibility and documentation requirements vary.
The goal is to create a clear paper trail so your lender can verify the source of the funds.
5. Your Employment or Income Doesn’t Meet the Lender’s Requirements
A good income doesn’t automatically mean a lender will use all of it when qualifying you.
How your income is treated can depend on how you’re paid and how established that income is. A salaried employee with a long employment history may be assessed differently from someone who is self-employed, paid hourly, earns commissions, works seasonally or has recently started a new job.
Self-employed borrowers can face additional documentation requirements because taxable income doesn’t always tell the complete story of a business owner’s finances. Variable or fluctuating income can also require the lender to consider an established history rather than simply your most recent paycheque.
A recent job change or probationary period may also require additional consideration depending on the lender and your circumstances.
This is an area where lender guidelines can differ considerably. I can review how your income is earned and determine which lenders may be better suited to your employment situation.
6. The Appraisal Comes In Too Low
You and the seller may agree that a home is worth a certain amount, but that doesn’t necessarily mean the lender will reach the same conclusion.
A lender may require an appraisal to establish the property’s value. If the appraised value is lower than the agreed purchase price, the lender may base its financing on the lower value.
For example, imagine you agree to purchase a home for $650,000, but the lender accepts a value of only $625,000. That $25,000 difference can affect the amount the lender is prepared to finance.
Depending on the circumstances, you may need additional funds to cover a shortfall or explore whether another solution is available. This can be particularly stressful if you’ve already committed to the purchase, which is why financing conditions and professional advice can be so important.
7. You Don’t Pass the Mortgage Stress Test
You might be comfortable making the mortgage payment at the rate you’ve been offered and still have difficulty qualifying.
That’s because Canadian mortgage qualification can require you to demonstrate that you could afford payments at a higher qualifying rate.
Most borrowers must qualify at the greater of their mortgage contract rate plus 2% or 5.25%, although certain exceptions may apply. The purpose is to test whether you could continue to afford the mortgage if interest rates or other household costs increased.
That means the amount you’re able to qualify for may be lower than what you’d expect from simply looking at the payment associated with your actual mortgage rate.
If the stress test is the obstacle, I can help you understand the numbers and assess what options may be appropriate rather than simply guessing at a different purchase price.
8. Your GDS or TDS Ratios Are Too High
Lenders don’t look only at how much money you earn. They also look at how much of that income is already committed to housing costs and other debts.
Two calculations you’ll often hear about are your Gross Debt Service (GDS) ratio and Total Debt Service (TDS) ratio.
GDS measures the portion of your gross income required for qualifying housing expenses. TDS goes further by including other debt obligations, such as car loans, lines of credit and credit card debt.
For CMHC-insured mortgages, for example, maximum debt-service thresholds are generally 39% for GDS and 44% for TDS. Individual circumstances and lender or insurer guidelines still matter.
This is why someone with a high salary may have trouble qualifying. A large car payment, significant credit card balances or other monthly debt commitments can reduce how much room you have for mortgage payments.
Before applying, I can calculate these ratios with you and identify whether existing debts may affect the mortgage amount you can qualify for.
9. You’ve Recently Applied for More Credit or Changed Your Finances
Your financial picture shouldn’t be treated as frozen the moment you’re pre-approved.
Applying for new credit, financing a vehicle, increasing credit card balances or taking out another loan before your mortgage closes can change the information a lender used to qualify you.
Several recent credit inquiries may also prompt questions about why you’re seeking additional credit.
This is why I encourage clients to speak with me before making significant financial changes between pre-approval and closing. Something that appears manageable on its own could affect your debt ratios or the lender’s assessment of the overall application.
Getting pre-approved is an important step, but you still need to maintain the financial circumstances that supported that approval.
10. You’re Applying With a Lender That Isn’t the Right Fit
One of the most important things to understand after a mortgage decline is that lenders don’t all assess applications in exactly the same way.
Banks, credit unions, monoline lenders, and alternative or private lenders may have different policies, documentation requirements, and risk tolerances. A borrower who doesn’t meet one lender’s guidelines may have circumstances that another lender assesses differently.
That doesn’t mean you should immediately send applications to as many lenders as possible. Multiple applications without first understanding the problem can create more confusion.
Instead, I start by identifying why the application didn’t work. Once we understand the obstacle, we can determine whether another lender or mortgage option appropriately addresses it.
What to Do If You Have Been Declined for a Mortgage
Being declined can be frustrating, particularly if you thought you had done everything necessary to prepare. But a decline gives us an important piece of information: something about the borrower, property or application didn’t meet that lender’s requirements.
The next step is finding out what that something was.
I generally recommend:
- Finding out why the lender declined the application. The appropriate next step depends on whether the issue involves credit, income, debt ratios, the property, down payment documentation or another underwriting concern.
- Reviewing your credit report and debts. If credit or your TDS ratio is creating a problem, we can look at what is affecting the application before trying again.
- Checking your documentation. Income and down payment issues can sometimes be related to the available documentation rather than to the amount of money you actually earn or have saved.
- Reconsidering the mortgage amount or property if necessary. If affordability or the appraisal is the problem, changing the purchase budget may be one possible solution.
- Avoiding a rush of new applications. I prefer to understand the reason for the original decline before deciding which lender or product to approach next.
- Creating a plan if you aren’t ready yet. Sometimes the right answer is to improve credit, reduce debt, establish more income history or save additional funds before reapplying.
The best next step depends entirely on why you were declined. That’s why I don’t recommend treating every mortgage decline the same way.
How a Mortgage Broker Can Help After a Decline
One advantage of working with a mortgage broker is that I can look beyond a single lender.
I have access to dozens of lenders, including banks, credit unions and other lending options. More importantly, I can help determine which lenders are appropriate for your circumstances rather than simply submitting the same application everywhere.
If you’ve been declined, I’ll review your application and consider factors such as your credit history, income, employment, debt obligations, down payment, and the property itself.
From there, I can help you understand what caused the problem and what realistic options may exist.
In some situations, another lender may have guidelines that are a better fit. In others, the best approach may be to make changes before applying again. Alternative or private lending can also be appropriate in certain circumstances, but these options may have different rates, fees, and risks and should be considered carefully.
My role is to help you understand those trade-offs so you can make an informed decision rather than simply chasing an approval.
Frequently Asked Questions
Can I get a mortgage after being declined?
Potentially, yes. A decline from one lender doesn’t automatically mean every lender will reach the same decision. The reason for the decline matters. I recommend identifying the problem first, then determining whether another lender or a change to your application is the appropriate solution.
Will being declined for a mortgage hurt my credit score?
The decline itself isn’t the same thing as a negative item such as a missed payment. However, applying for credit can result in an inquiry on your credit file. Rather than repeatedly applying with different lenders on your own, it’s better to understand why the original application was declined.
Can another lender approve me after my bank says no?
It’s possible. Lenders can have different underwriting guidelines and risk tolerances. A decline from your bank may mean your application doesn’t meet that bank’s specific criteria, rather than that no mortgage option exists.
What happens if I fail the mortgage stress test?
Failing the stress test generally means you don’t qualify for the requested mortgage under the applicable qualifying calculation. We can review your purchase price, down payment, debts, income and other factors to see what is affecting your qualification and what options may be available.
How long should I wait before applying again?
There’s no single waiting period that applies to every mortgage decline. If the issue can be addressed quickly, you may be able to reconsider your options sooner. If you need to establish a longer income history, rebuild credit, reduce debt or save more money, waiting may be the better strategy.
Can I be declined after I’ve been pre-approved?
Yes. A pre-approval isn’t the same as final mortgage approval. The lender still needs to approve the complete application and property, and changes to your employment, debt, credit or finances before closing can affect the outcome.
A Mortgage Decline Doesn’t Have to Be the End of the Conversation
There are many reasons you may be declined for a mortgage, and some aren’t obvious until a lender reviews the complete application.
Being prepared is one of your best defences against surprises. Before you make an offer, or if you’ve already received a decline, I can review your circumstances, help identify potential challenges, and walk you through the mortgage options that may be available to you.
If you’re buying a home in Ottawa or elsewhere in Ontario and have questions about mortgage qualification, contact me. I’ll help you understand where you stand and what your next step could look like.
Recent Posts
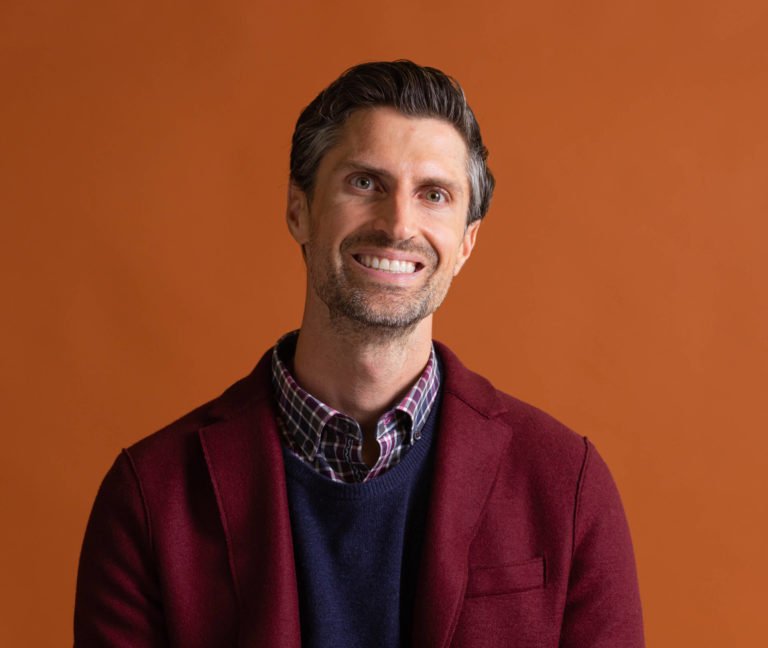
Andrew Thake is a seasoned mortgage broker with over 15 years of industry experience. He’s assisted more than 2,200 clients in finding their ideal mortgage solutions. Recognized for his excellence, Andrew has received high honours and awards, including the National Rookie of the Year from TD Canada Trust and recognition as a Top 10 Ottawa Mortgage Broker in 2023. He has also been inducted into the Hall of Fame at Dominion Lending Centres and has consistently received their Platinum Award during his tenure as a mortgage broker.
Andrew’s dedication lies in serving his clients and prioritizing their needs with an empathetic approach. Throughout the application process, he provides tailored, informed, and efficient services to ensure the best mortgage solutions for his client’s unique circumstances. The best part of Andrew’s job is when he gets to see the joy on his clients’ faces following their mortgage approval.