
If you’re planning to buy a home or renew your mortgage in 2027, there’s a good chance you’re wondering where interest rates are headed.
Will mortgage rates continue to rise? Could they start falling again? And should you choose a fixed or variable mortgage? These are questions I hear regularly from homebuyers and homeowners in Ottawa. While nobody can predict interest rates with certainty, understanding the current forecasts and what influences mortgage rates can help you make a more informed decision.
The important thing to remember is that choosing the right mortgage isn’t just about predicting interest rates. It’s about finding an option that works for your finances, your future plans, and your comfort level.
Where Are Canadian Mortgage Rates Heading in 2027?
As of October 2026, several major Canadian banks expect interest rates to increase gradually in 2027, although there’s no consensus on how quickly or how much they might rise.
According to forecasts compiled by WOWA, RBC, Scotiabank, CIBC, and National Bank anticipate some increases in the Bank of Canada’s policy rate during 2027. Meanwhile, TD and BMO expect the policy rate to remain relatively stable.
The Bank of Canada’s policy rate currently sits at 2.25%, following its September 2026 announcement.
These forecasts suggest that borrowers should be prepared for the possibility of higher rates, but they don’t guarantee that mortgage rates will rise. Economic conditions can change quickly, and forecasts are regularly revised as new information becomes available.
It’s also important to understand that fixed and variable mortgage rates don’t necessarily move in the same direction.
What Could Influence Mortgage Rates in 2027?
Several economic factors will help determine where Canadian mortgage rates go next.
Inflation
Inflation remains one of the biggest influences on interest rates. If the cost of goods and services rises faster than expected, the Bank of Canada may need to maintain higher interest rates or increase them to help control inflation. If inflation remains under control and the economy slows, there may be less pressure to raise rates.
Employment and Economic Growth
The Bank of Canada also monitors employment, consumer spending, and overall economic activity. A strong economy can create upward pressure on interest rates, while weaker economic conditions may encourage the Bank to hold rates steady or consider reductions.
Government of Canada Bond Yields
Here’s something that often surprises homeowners: fixed mortgage rates can change even when the Bank of Canada doesn’t make an announcement. That’s because fixed mortgage rates are influenced heavily by Government of Canada bond yields, particularly for comparable mortgage terms. When bond yields rise, fixed mortgage rates often follow. When bond yields decline, lenders may have room to offer lower fixed rates.
Variable mortgage rates, on the other hand, are generally tied to a lender’s prime rate, which tends to move in response to changes in the Bank of Canada’s policy rate. Understanding this difference can help explain why mortgage rates sometimes move differently than expected.
Should You Choose a Fixed or Variable Mortgage in 2027?
This is one of the most common mortgage questions I receive, and there’s no single answer that works for everyone.
Both fixed and variable mortgages have advantages. The better choice depends on your financial situation, priorities, and tolerance for interest rate changes.
Fixed-Rate Mortgages
A fixed-rate mortgage keeps your interest rate the same throughout your mortgage term. This provides stability and predictable payments, which can make household budgeting easier.
A fixed mortgage may appeal to you if you prefer certainty, have a tighter monthly budget, or simply don’t want to worry about interest rate fluctuations. However, fixed mortgages can come with higher penalties if you need to break your mortgage before the end of the term, depending on the lender and mortgage agreement.
Variable-Rate Mortgages
With a variable-rate mortgage, your interest rate can change when your lender adjusts its prime rate.
What many people don’t realize is that not all variable-rate mortgages handle payments the same way. Some have adjustable payments, meaning your mortgage payment rises or falls when interest rates change. Others have fixed payments, where your regular payment may stay the same even when interest rates change. Instead, the amount going toward interest and principal adjusts.
With fixed-payment variable mortgages, rising interest rates can slow down how quickly you repay your mortgage. Depending on the lender and mortgage terms, you could also reach a trigger rate or face other payment adjustments.
Variable mortgages may offer advantages, including potentially lower rates and, with many lenders, more predictable penalties if you need to break your mortgage early. However, they also involve uncertainty.
Which One Makes More Sense?
Rather than trying to guess exactly where rates will be in a year or two, I encourage clients to consider a few practical questions.
- How comfortable would you be if interest rates increased?
- Do you expect to move, refinance, or make changes to your mortgage during the term?
- Would predictable payments help you feel more comfortable, or are you willing to accept some uncertainty for the potential benefits of a variable rate?
It’s also worth comparing different term lengths. A 3-year fixed mortgage, for example, might offer a different balance of stability and flexibility than a 5-year fixed mortgage.
The lowest rate isn’t always the best mortgage, and the right decision will depend on your circumstances.
How Can Ottawa Homebuyers and Homeowners Prepare for 2027?
If you’re hoping to purchase a home in Ottawa in 2027, I’d recommend focusing on what you can control rather than waiting for interest rates to reach a particular number.
For Ottawa Homebuyers
Start With a Mortgage Pre-Approval
A mortgage pre-approval can help you establish a realistic purchase budget and understand how much you may qualify to borrow. Depending on the lender, you may also be able to secure an interest rate hold while you’re shopping for a home.
A rate hold can offer some protection if rates increase, although the final mortgage approval and available rate will depend on the lender’s requirements, your finances, and the property you purchase.
Focus on Your Comfortable Monthly Payment
Just because you qualify for a particular mortgage amount doesn’t necessarily mean you should borrow the maximum. Consider how your mortgage payments will fit alongside property taxes, utilities, insurance, maintenance, and your other financial priorities.
It’s also worth thinking about how your budget might change over the next few years. The goal should be to purchase a home you can comfortably afford, not simply to qualify for the largest mortgage possible.
Don’t Try to Time the Market Perfectly
Waiting for lower mortgage rates can be tempting, but it’s difficult to predict exactly when rates will change. Even if mortgage rates decline, home prices, competition, and other market conditions could change in the meantime.
Your decision to purchase should be based on your financial readiness, housing needs, and long-term plans rather than interest rate forecasts alone. No matter where next year’s rates go, several practical steps can help you prepare for your upcoming mortgage decision.
For Ottawa Homeowners Renewing in 2027
If your mortgage is coming up for renewal in 2027, now is a good time to start thinking about your options.
One of the biggest mistakes homeowners make is assuming their existing lender will automatically offer them the most competitive rate. Your lender’s initial renewal offer is a starting point, not necessarily your best available option.
Start Reviewing Your Options Early
I generally recommend exploring your options around 4 months before your renewal date. This allows time to compare lenders, review mortgage features, and make an informed decision without feeling rushed.
Some lenders may also offer rate holds ahead of renewal, providing additional flexibility if market conditions change.
Compare More Than Just the Rate
While getting a competitive interest rate is important, there are other features worth considering. Prepayment privileges, penalties for breaking your mortgage early, portability, and the ability to make changes during your mortgage term can all affect the overall value of your mortgage.
For example, a mortgage with a slightly higher interest rate but more favourable features could be a better fit if you expect to move or make a substantial lump-sum payment. Switching lenders may also be worthwhile, although eligibility requirements, potential fees, and the type of mortgage you currently have can influence your options.
Review Your Current Lender’s Offer
Before making your renewal decision, request the available renewal options from your existing lender. This provides a useful starting point for comparing what else may be available.
As an Ottawa mortgage broker, I can help you evaluate those offers alongside alternatives from other lenders, taking into account the rates, terms, and features that matter most to you. The goal isn’t necessarily to switch lenders. It’s to make sure you’re making an informed decision before committing to another mortgage term.
Making the Right Mortgage Decision in 2027
Interest rate forecasts can be helpful, but they’re only one piece of the mortgage puzzle.
After more than 20 years of experience in the mortgage industry, one thing I’ve learned is that there’s rarely a single mortgage option that’s right for everyone. Some homeowners value predictable payments above everything else. Others place a higher priority on flexibility, prepayment options, or finding the lowest available rate.
What’s most important is understanding your choices and selecting a mortgage that fits your needs.
Whether you’re purchasing your first home, moving, refinancing, or approaching renewal, I can help you compare mortgage options from a wide range of lenders and make an informed decision.
If you’d like to review your mortgage options for 2027, let’s schedule a call.
This article reflects information and forecasts available as of October 24, 2026. Interest rate forecasts are subject to change, and mortgage products, rates, and eligibility depend on individual circumstances and lender approval.
Frequently Asked Questions About Mortgage Rates in 2027
Will Canadian Mortgage Rates Go Down in 2027?
It’s possible, but current forecasts as of October 2026 suggest that interest rates may remain stable or rise rather than decline significantly.
Economic conditions, inflation, and Government of Canada bond yields will all play a role.
Remember that fixed mortgage rates can decrease even if the Bank of Canada doesn’t lower its policy rate.
Should I Lock Into a Fixed Mortgage Before Rates Rise?
That depends on your circumstances.
A fixed mortgage can provide valuable certainty, but choosing one solely because rates are expected to rise may not be the best approach.
It’s worth comparing fixed and variable options, different term lengths, mortgage features, and the potential costs of making changes before your term ends.
Is a 3-Year or 5-Year Fixed Mortgage Better in 2027?
Neither is automatically better.
A 3-year fixed mortgage allows you to revisit your mortgage sooner, while a 5-year fixed mortgage provides a longer period of rate stability.
The difference in rates, potential penalties, and your future plans should all factor into your decision.
How Early Can I Start Shopping for a Mortgage Renewal?
A good starting point is approximately 4 months before your mortgage renewal date.
This gives you time to review your current lender’s offers, explore competing options, and consider whether your financial needs have changed.
Should I Wait for Mortgage Rates to Fall Before Buying a Home?
Not necessarily.
Interest rates are just one part of the decision. Your income, savings, affordability, housing needs, and local real estate market conditions may be more important than trying to predict short-term movements in rates.
Recent Posts
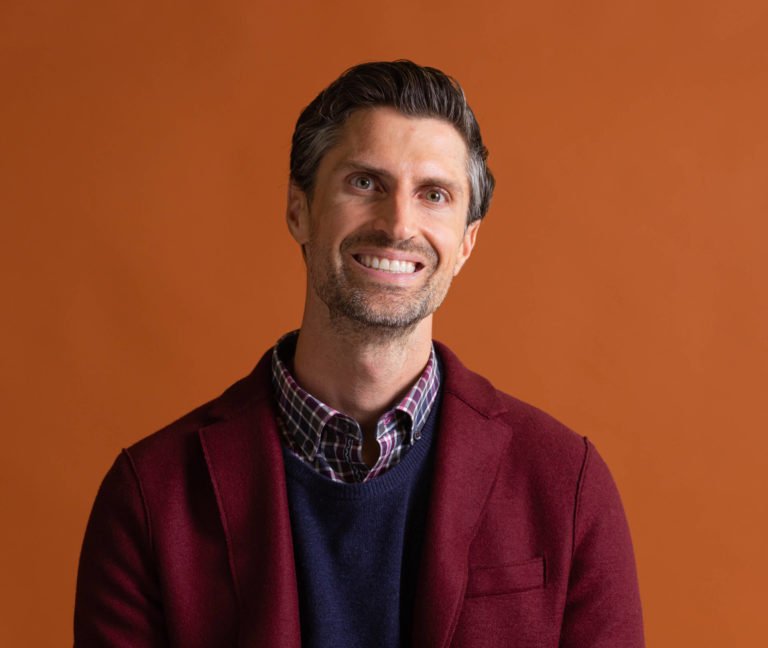
Andrew Thake is a seasoned mortgage broker with over 15 years of industry experience. He’s assisted more than 2,200 clients in finding their ideal mortgage solutions. Recognized for his excellence, Andrew has received high honours and awards, including the National Rookie of the Year from TD Canada Trust and recognition as a Top 10 Ottawa Mortgage Broker in 2023. He has also been inducted into the Hall of Fame at Dominion Lending Centres and has consistently received their Platinum Award during his tenure as a mortgage broker.
Andrew’s dedication lies in serving his clients and prioritizing their needs with an empathetic approach. Throughout the application process, he provides tailored, informed, and efficient services to ensure the best mortgage solutions for his client’s unique circumstances. The best part of Andrew’s job is when he gets to see the joy on his clients’ faces following their mortgage approval.